
The Federal Government has ruled out a return to fuel subsidies and multiple exchange rates, insisting that its economic reforms will remain in place as it seeks to boost investment, economic growth and job creation.
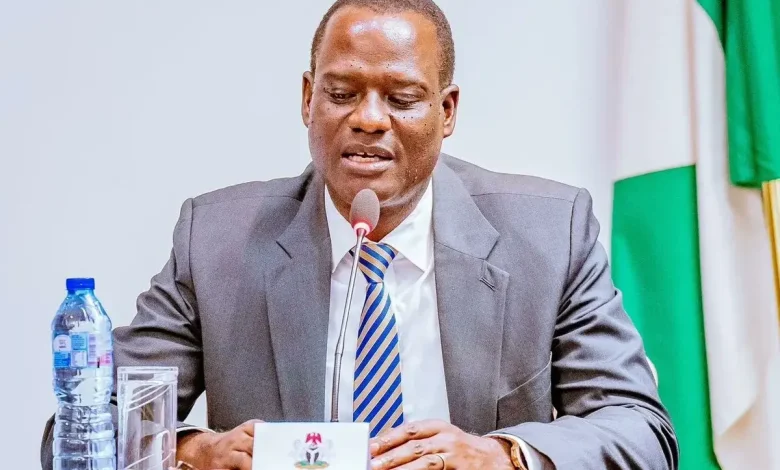
The Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, stated this on Saturday during a briefing following Nigeria’s participation in the International Monetary Fund (IMF) and World Bank Group Annual Meetings in Bangkok, Thailand.
Oyedele said the government remained committed to its current economic policy direction, despite the challenges Nigerians continue to face.
“Let me be clear: there will be no return to fuel subsidies or multiple exchange rates,” he said.
FG Explains NNPC’s Petrol Price Discount
The minister also clarified that the 30-day retail margin discount on petrol introduced by the Nigerian National Petroleum Company Limited (NNPC) should not be mistaken for a return to fuel subsidy.
According to Oyedele, the initiative was a temporary commercial decision intended to reduce retail margins and provide some relief to consumers, rather than a subsidy funded with public money.
The clarification comes amid continued public concern about petrol prices and the cost of living following the removal of fuel subsidies.
Nigeria’s Economy Grows by 4.4%
Oyedele highlighted several economic indicators that he said showed progress under the government’s reform programme.
He disclosed that Nigeria’s economy grew by 4.4 per cent in the second quarter of 2026, while inflation had declined for four consecutive months to less than half its peak level recorded about two years earlier.
The minister also said Nigeria’s foreign reserves had risen above $35 billion.
He added that the country’s tax-to-GDP ratio increased from about seven per cent three years ago to 12.5 per cent at the end of 2025, following the rebasing of the economy.
According to him, private capital inflows rose from approximately $300 million in 2023 to nearly $6 billion in 2026, representing an increase of about 20 times.
Oyedele put Nigeria’s debt at approximately 36 per cent of gross domestic product (GDP), describing the debt profile as manageable.
He said the government was also shifting towards cheaper, longer-term financing to reduce borrowing costs.
The minister maintained that the next priority was to translate these gains into more investment, faster economic growth and better employment opportunities.
World Bank, IMF and EU Signal Continued Cooperation
Oyedele said the World Bank Group had reaffirmed its support for Nigeria’s power and infrastructure sectors through guarantee instruments and other financing mechanisms.
He added that the IMF had pledged continued technical assistance in fiscal policy implementation, transparency and national statistics.
The European Union, he said, had identified energy and local pharmaceutical manufacturing as priority areas for collaboration under its Global Gateway programme.
However, the minister cautioned against interpreting these engagements as confirmed financial disbursements.
“These are commitments to work together with us, not announcements of money,” he said.
Oyedele explained that the government would only report progress as confirmed agreements when commitments had been signed and tangible results began to emerge.
Nigeria Pushes for Reforms to Global Financial System
The minister also said Nigeria used its position as chair of the Group of 24 (G24) to advocate changes to the global financial system.
The proposals included strengthening the IMF’s quota-based structure, improving transparency in credit-rating methodologies, expanding local-currency markets and increasing access to affordable climate finance.
Oyedele cited findings presented by the United Nations Economic Commission for Africa indicating that developing countries paid about $500 billion more annually to borrow than advanced economies.
He described the additional borrowing costs faced by African countries as a “prejudice premium”, arguing that the risk attached to the continent did not always reflect the economic conditions of individual countries.
He also expressed support for establishing an African credit-rating agency to help countries with credible economic policies access more affordable financing.
On energy policy, Oyedele maintained that natural gas remained Nigeria’s transition fuel and called for climate-financing arrangements that account for differences in countries’ stages of development.
FG Unveils $78.5bn Investment Pipeline
Oyedele further disclosed that the Federal Government had unveiled 65 investment projects valued at $78.5 billion under the Project Nigeria initiative.
The projects cover key sectors, including energy, transportation, industry, mining, agriculture, healthcare and services.
According to the minister, each project is backed by a feasibility study and designed to accommodate participation from local and foreign private investors.
He added that investors from Asia and Europe had submitted expressions of interest in the projects.
The government hopes the investment pipeline will help attract private capital, expand economic activity and create jobs as it continues with its current economic reforms.